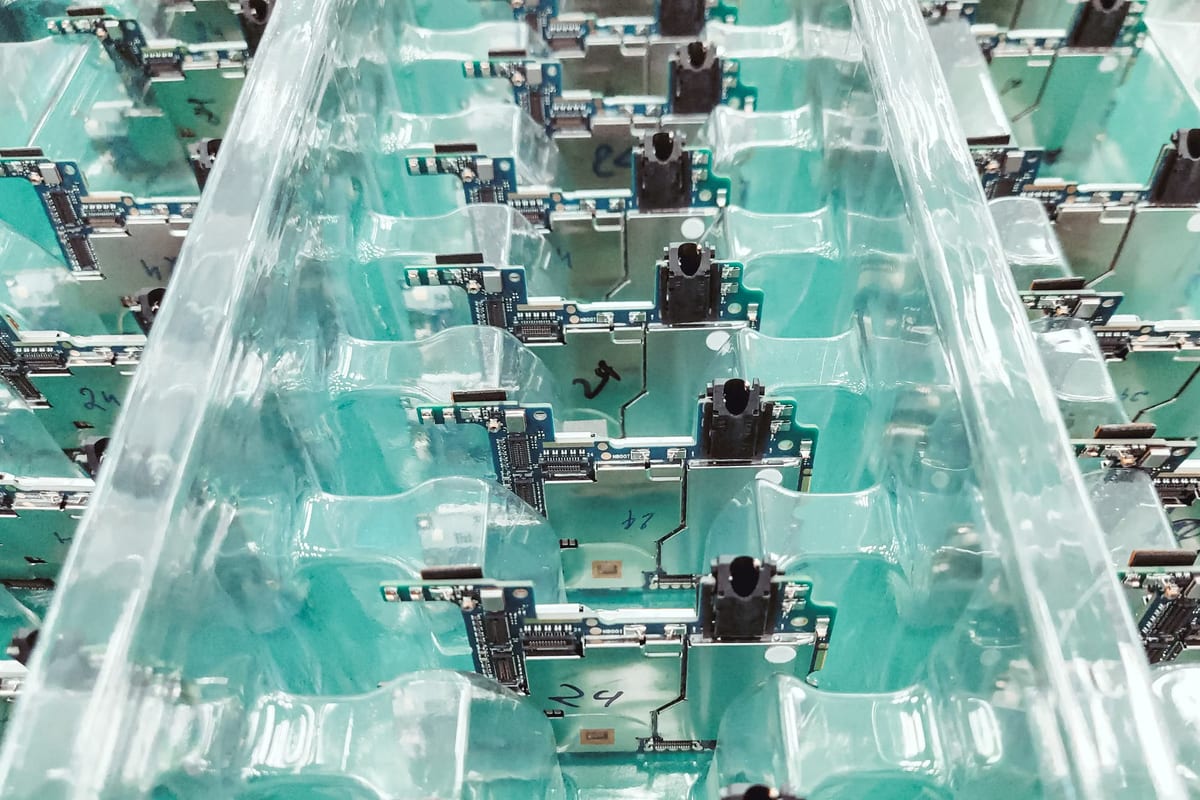
Software investors are used to a particular shape of risk: build cost is front-loaded, marginal cost is near zero, and the worst case is that nobody buys. Hardware breaks all three assumptions, and sports technology is full of businesses that are hardware companies wearing software margins in their pitch deck.
This is how we underwrite them. It is not a reason to decline — some of the most defensible positions in this sector require physical deployment — but it changes the questions, the capital plan and the milestones.
The three risks that actually matter
Working capital. A company shipping sensors, gateways, scanners or wearables must buy components, hold inventory and often deploy before it invoices. In a seasonal industry, that spending clusters: units must be built in the close season, installed before the opening fixture, and paid for on terms the buyer sets. The cash gap between component purchase and customer payment is frequently the binding constraint on growth, and it is invisible in a revenue chart.
Inventory obsolescence. Components are bought in batches to get a price. A design revision, a supplier end-of-life notice or a certification change can strand a batch. In sport there is an additional cause: a competition changes a technical regulation and the installed base no longer complies.
Field failure and service. A software bug is fixed by a deploy. A hardware fault requires a person, in a stadium, between fixtures, with a spare. The cost of that person is real, recurring and almost always underestimated in the first financial model we are shown.
The question is never whether the hardware works. It is what a unit costs to land, to service for five years, and to replace when the venue changes its network.
What we ask for
We look for a small set of artefacts. Their absence is more informative than their contents.
- A bill of materials with two prices Cost at current volume and cost at a realistic twelve-month volume, with the components most exposed to supply constraints identified by name.
- Landed cost, not unit cost Including freight, duty, certification, packaging, spares provisioning and the labour of installation. The gap between these two numbers is usually large.
- A cash conversion cycle Days of inventory, days of receivables, days of payables, and how each moves across a season. A company that cannot produce this has not yet met its real constraint.
- Failure data from the field Return rates, mean time between failures, and the causes. Early-stage companies rarely have much; what matters is whether they are collecting it systematically.
- A certification map Radio and electromagnetic compliance for each market of operation, plus any venue or competition-specific approval. Certification timelines are long and are not compressible with money.
Where the balance sheet should sit
One of the more consequential decisions a hardware-adjacent founder makes is who owns the device. Three models are common, and they produce very different companies.
Sell the hardware. Simple, cash-positive at deployment, and it caps the upside because the recurring revenue is only the software. It also transfers the replacement decision to the customer, which is bad news when a five-year-old unit becomes a support burden.
Bundle it into a subscription. Better economics over time and a cleaner buying decision, but the company finances the asset. This is where venture equity is most often misused: equity is expensive capital for a depreciating physical asset, and a company that funds three years of device deployment from an equity round has effectively bought inventory at a venture cost of capital.
Separate the financing. The device is financed by an asset-backed facility, a leasing partner or the customer’s own capital budget, while the company sells software and service. This is usually the right answer once volume justifies the arrangement overhead, and the founders who have thought about it are the ones we take most seriously.
We do not fund inventory with equity beyond the point where a debt or leasing structure becomes available. Part of the work after our investment is helping a company reach that point and introducing it to lenders who understand seasonal receivables.
Seasonality, modelled honestly
A sports hardware business has a revenue shape that looks alarming to anyone used to monthly software growth: long flat stretches, then a cluster of deployments in a few weeks. The correct response is not to smooth it in the model but to plan around it. That means a cash plan built on the worst month, an installation team sized for the peak with a credible plan for the trough, and a component ordering cycle that starts before the contracts are signed — which is itself a risk that has to be sized deliberately rather than discovered.
It also means the milestones for the next round should be set at a point in the season where the evidence exists. Raising in the middle of a deployment trough, with three months of flat revenue behind you, is an avoidable own goal.
When hardware is worth it
Despite all of this, we invest in these companies, for one reason: physical presence in a venue is the most durable position in the sector. A scanner at a gate, a sensor array on a pitch or a network installed in a stand is not replaced casually. Switching costs are measured in close-season weeks that a venue operator does not have.
So the calculus is straightforward. If the hardware buys a position that software alone cannot reach, and if the founder demonstrates command of landed cost, cash conversion and service economics, we are interested. If the hardware exists because the software could not be sold on its own, we are not.
The founders who do this well have one thing in common. They talk about the operational realities — freight, spares, a fitter’s day rate, a certification renewal — with the same fluency they bring to the product. That fluency is not a detail. In a physical business it is the whole of the discipline.